Medical Image Analysis Software Market Size & Share 2035
Market Overview
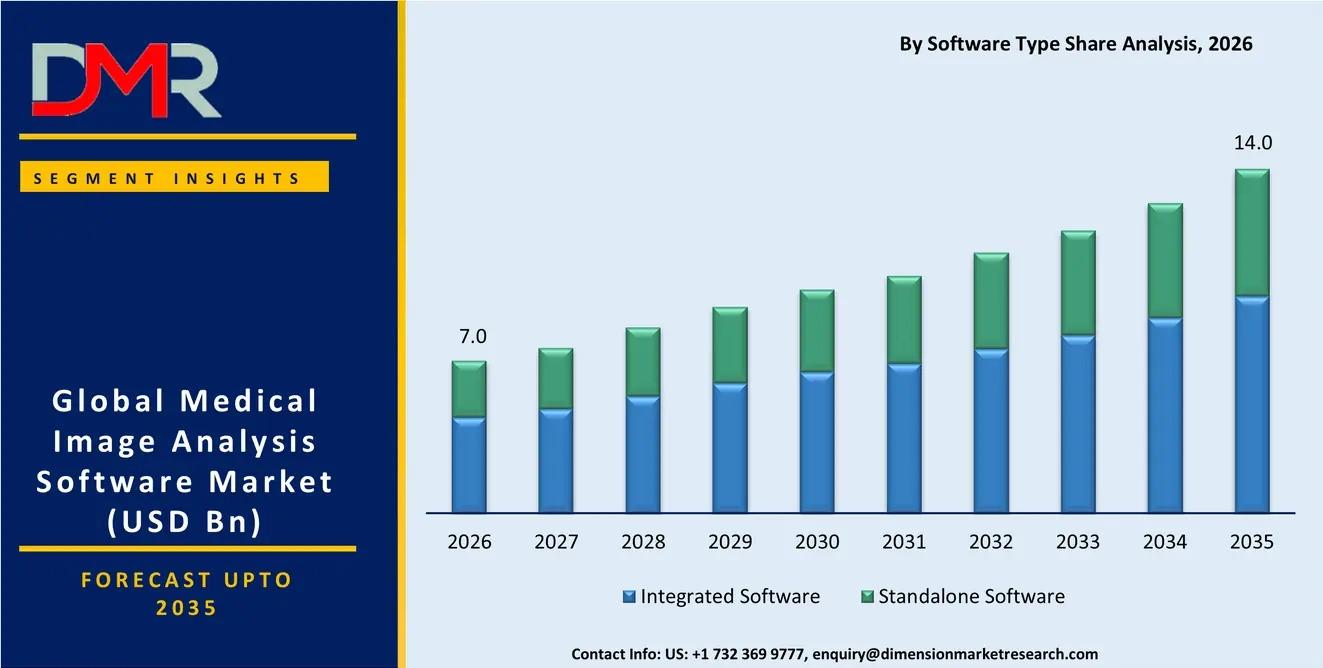
According to Dimension Market Research, the Global Medical Image Analysis Software Market is projected to be valued at USD 7.0 billion in 2026, which is further projected to reach USD 14.0 billion by 2035, expanding at a compound annual growth rate (CAGR) of 8.0% across the forecast period. The market is witnessing robust growth due to the exponential rise in diagnostic imaging volumes, the accelerating clinical integration of artificial intelligence and deep learning algorithms, and the proliferation of cloud-native PACS architectures.
Growth is being propelled by the exponential rise in diagnostic imaging volumes across computed tomography, magnetic resonance imaging, ultrasound, and X-ray modalities, coupled with the accelerating clinical integration of artificial intelligence and deep learning algorithms that automate lesion detection, quantitative measurement, and longitudinal disease tracking. The proliferation of cloud-native picture archiving and communication system (PACS) architectures, the tightening interoperability between radiology information systems (RIS) and electronic health records (EHR), and expanding reimbursement pathways for AI-assisted image interpretation are reshaping the diagnostic imaging software landscape.
Investment is intensifying as health systems pivot from manual, radiologist-dependent image review toward algorithm-augmented, workflow-integrated image analysis platforms designed to compress reporting turnaround time, elevate diagnostic consistency, and mitigate the global shortage of trained radiologists.
The market is also being shaped by the integration of generative AI into structured reporting, the emergence of precision imaging and multi-modal biomarker-guided diagnostics, and the convergence of radiology, cardiology, and pathology imaging workflows into unified enterprise imaging platforms.
Definition and Market Significance
Medical image analysis software refers to specialized applications and platforms that process, analyze, and interpret diagnostic medical images from modalities including CT, MRI, PET, ultrasound, and X-ray. These solutions encompass integrated software embedded within PACS, RIS, and EHR systems, as well as standalone software for specialized AI-powered image analysis and diagnostic applications.
The importance of medical image analysis software lies in its critical role in improving diagnostic accuracy, reducing radiologist workload, standardizing quantitative reporting, and enabling faster clinical decision-making. As imaging volumes continue to grow globally and the shortage of trained radiologists intensifies, these solutions become essential for maintaining timely and consistent diagnostic services.
Medical image analysis software also supports broader healthcare innovation by enabling precision medicine, accelerating drug discovery through quantitative imaging biomarkers, improving cancer detection and treatment response monitoring, and facilitating multi-disciplinary care coordination across radiology, oncology, cardiology, and neurology.
Looking for Something Specific? Get Free Sample:
https://dimensionmarketresearch.com/request-sample/medical-image-analysis-software-market/
Market Drivers
A major factor driving the Medical Image Analysis Software Market is the escalating global diagnostic imaging volumes and chronic disease burden. The relentless rise in cancer incidence, cardiovascular disease, and neurodegenerative conditions is driving sustained growth in diagnostic imaging procedure volumes across CT, MRI, ultrasound, and nuclear medicine modalities worldwide. The unabated expansion of aging populations, coupled with broadening population-level cancer and cardiovascular screening programs, is enlarging the pool of patients requiring repeated, longitudinal imaging assessment.
Expanding regulatory clearance and clinical validation of AI-enabled algorithms is another key driver supporting market expansion. A growing wave of regulatory clearances for AI- and deep learning-based image analysis algorithms across oncology, cardiology, neurology, and breast imaging applications has repositioned computer-aided detection and quantification software as a mainstream component of the diagnostic imaging workflow rather than a niche research tool. The robust diagnostic accuracy and workflow efficiency benefits demonstrated in large-scale multi-reader, multi-case validation studies have triggered major updates to radiology society clinical guidance.
The deepening integration of image analytics into oncology, cardiology, and neurology care pathways is also contributing to market growth, along with expanding reimbursement codes for AI-assisted radiology interpretation and the digital transformation of hospital imaging infrastructure.
Market Trends
The integration of medical image analysis into enterprise imaging and multidisciplinary care platforms is emerging as an important trend in the market. A defining trend is the dissolution of silos between radiology, cardiology, pathology, and oncology imaging workflows, driven by the shared demand for a unified, longitudinal patient imaging record. Clinical practice is consolidating around enterprise imaging platforms that simultaneously support diagnostic radiology, cardiac imaging, and digital pathology within a single vendor-neutral archive.
Another significant trend is the emergence of generative AI-enabled structured reporting and workflow automation. Generative AI, augmented by large language models trained on radiology reporting corpora, is transforming the interpretation and documentation phase of the imaging workflow. AI models trained on annotated image-report pairs can now draft structured preliminary reports, auto-populate standardized measurement templates, and flag discrepancies between imaging findings and prior reports with increasing accuracy.
The increasing use of cloud-based and hybrid PACS/VNA infrastructure, along with the rise of precision imaging and radiomics-based diagnostics, is also transforming the market.
Market Restraints
Despite its strong growth potential, the Medical Image Analysis Software Market faces certain limitations. High implementation costs and interoperability barriers across legacy imaging infrastructure pose significant challenges. Despite demonstrable clinical and workflow benefits, the deployment of advanced image analysis software imposes substantial financial and technical burdens on hospitals and diagnostic centers, particularly in low- and middle-income countries where legacy PACS infrastructure and constrained capital budgets limit adoption.
Integrating AI-enabled analysis tools with fragmented, vendor-specific imaging archives requires significant IT investment, specialized data governance protocols, and ongoing algorithm validation, limiting reach in rural and resource-constrained healthcare settings.
In addition, even in high-income nations, enterprise-wide deployment costs and the administrative burden of algorithm monitoring and revalidation create sustained pressure on hospital IT budgets and vendor procurement cycles. Algorithm bias, cybersecurity vulnerabilities, and data quality issues also create risks that can slow adoption.
Market Opportunities
The expansion of cloud-based and hybrid imaging infrastructure presents significant growth opportunities. The global shift toward cloud-based and hybrid PACS/VNA architectures represents a high-growth opportunity for software vendors, cloud infrastructure providers, and managed imaging service companies. Health systems are increasingly favoring subscription-based, software-as-a-service image analysis platforms that reduce capital expenditure while enabling elastic computing capacity for AI inference at scale.
Precision imaging and multi-modal biomarker-guided diagnostics is another promising opportunity. Emerging radiomic and multi-modal imaging biomarkers are enabling precise disease characterization beyond conventional qualitative image review. This paves the way for a precision imaging market where quantitative imaging phenotypes are matched to specific disease subtypes and treatment response profiles. Software developers that commercialize validated, reimbursable radiomics and quantitative imaging biomarker platforms capable of predicting individual treatment response and disease trajectory will unlock a premium-priced analytics market.
Furthermore, the growth of multi-tenant cloud imaging platforms, federated learning architectures that preserve data sovereignty, and vendor-neutral archive solutions is expected to open new opportunities for market participants.
Segmentation
The Medical Image Analysis Software Market is categorized based on software type, deployment mode, imaging modality, image type, clinical application, and end user.
By software type, integrated software is projected to dominate with 58.4% of the market share. Its strong position is driven by seamless integration with PACS, RIS, and EHR platforms, allowing healthcare organizations to manage, analyze, retrieve, and share medical images through connected clinical workflows. Standalone software is expected to register the highest CAGR of 9.1%, driven by demand for specialized AI-powered image analysis and diagnostic applications.
By deployment mode, cloud-based deployment is expected to lead with 44.7% of the market share. Growing adoption is supported by remote accessibility, scalability, centralized data management, reduced infrastructure requirements, and easier integration of advanced imaging algorithms. Hybrid deployment is projected to grow at the highest CAGR of 11.2%, supported by flexible infrastructure requirements.
By imaging modality, computed tomography is projected to dominate with 31.6% of the market share. CT imaging generates extensive cross-sectional datasets that require advanced software for reconstruction, visualization, segmentation, measurement, and diagnostic interpretation. Magnetic resonance imaging is anticipated to register the highest CAGR of 9.8%, supported by advanced diagnostic applications.
By image type, 3D imaging is expected to dominate with 43.5% of the market share. The technology provides detailed anatomical visualization and enables clinicians to examine organs, tissues, tumors, bones, and vascular structures from multiple perspectives. 4D imaging is projected to record the highest CAGR of 10.4%, driven by dynamic visualization applications.
By clinical application, oncology is projected to dominate with 27.8% of the market share. Medical image analysis solutions are extensively utilized for tumor detection, characterization, segmentation, staging, treatment planning, therapy response assessment, and continuous disease monitoring. Cardiology is expected to register the highest CAGR of 10.1%, supported by growing cardiovascular imaging and quantitative assessment requirements.
By end user, hospitals are projected to dominate with 61.9% of the market share. Their leadership is attributed to high volumes of diagnostic imaging procedures, extensive installation of CT, MRI, ultrasound, X-ray, and PET systems, and increasing adoption of advanced digital imaging infrastructure. Diagnostic imaging centers are anticipated to register the highest CAGR of 8.7%, supported by growing outpatient diagnostic imaging demand.
Regional Analysis
North America is poised to lead the Global Medical Image Analysis Software Market with an estimated 41.6% revenue share in 2026. The region's dominance is anchored by a high-volume, well-reimbursed diagnostic imaging infrastructure, early and broad adoption of FDA-cleared AI image analysis algorithms, and the world's highest per-capita expenditure on enterprise imaging IT. The United States, in particular, is characterized by early adoption of cloud-based PACS and AI-assisted radiology workflow tools, robust commercial and public payer coverage for select AI-assisted imaging interpretation codes, and a dynamic health IT innovation ecosystem supported by federal digital health policy initiatives. The US market is projected to be valued at USD 2.4 billion in 2026, reaching USD 4.7 billion by 2035 at a CAGR of 7.5%.
Europe represents one of the largest regional markets, characterized by universal healthcare coverage models that provide comprehensive diagnostic imaging access, though with significant cross-national variation in cloud adoption and AI algorithm reimbursement. Germany holds the largest European market share, driven by its large radiology specialist workforce, high imaging equipment density, and broad reimbursement pathways for innovative diagnostic software. The European Society of Radiology's advocacy for standardized AI validation and the growing adoption of CE-marked AI algorithms are gradually improving enterprise imaging software penetration and structured reporting rates.
Asia Pacific is projected to register the fastest CAGR of 9.9% through 2035, driven by the region's enormous and rapidly expanding diagnostic imaging capacity, particularly in China and India, which together are scaling hospital imaging infrastructure at an unprecedented pace. Economic development is enabling massive investments in radiology IT modernization, with both public and private hospital networks rapidly deploying cloud-based image analysis platforms. Governments are implementing national radiology digitization and AI adoption initiatives that are boosting enterprise imaging software penetration.
Latin America is expanding as rising cancer and cardiovascular disease incidence, coupled with growing private diagnostic imaging center investment, drives diagnostic imaging procedure volumes upward. Brazil and Mexico are the primary national markets. The Middle East & Africa market is developing against a backdrop of substantial government healthcare digitization investment in GCC countries, with Saudi Arabia and the United Arab Emirates being the most attractive markets.
Purchase the Full Report
https://dimensionmarketresearch.com/checkout/medical-image-analysis-software-market/
Competitive Landscape
The Global Medical Image Analysis Software Market features a diverse competitive landscape spanning multinational imaging equipment and software conglomerates, dedicated AI diagnostic software innovators, enterprise imaging IT vendors, and emerging cloud-native health technology startups. GE Healthcare and Siemens Healthineers dominate the integrated PACS and enterprise imaging software market through extensive installed bases of imaging equipment bundled with native AI analysis capabilities. Philips Healthcare and Canon Medical Systems are leading providers of diagnostic imaging platforms and workflow software, competing on cloud connectivity, AI algorithm marketplaces, and vendor-neutral archive solutions.
Prominent players include Siemens Healthineers AG, GE HealthCare Technologies Inc., Koninklijke Philips N.V., Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Agfa-Gevaert N.V., Carestream Health, Inc., Sectra AB, Esaote S.p.A., MIM Software Inc., Aidoc Medical Ltd., Lunit Inc., INFINITT Healthcare Co., Ltd., AnalyzeDirect, Inc., AQUILAB SAS, Circle Cardiovascular Imaging Inc., ContextVision AB, Image Analysis Group Ltd., Kitware, Inc., Mach7 Technologies Ltd., Medis Medical Imaging Systems B.V., Novarad Corporation, QMENTA, TeraRecon, Inc., Visage Imaging, Xinapse Systems Ltd., Ziosoft, Inc., Blackford Analysis Ltd., Mirada Medical Ltd., RamSoft Inc., Quibim, Riverain Technologies, Subtle Medical Inc., Pie Medical Imaging B.V., Infervision Medical Technology Co., Ltd., Neusoft Medical Systems Co., Ltd., Deepwise Medical, Hologic, Inc., Butterfly Network, Inc., Spacelabs Healthcare, and Other Key Players. Recent developments include Aidoc's expanded FDA clearance for incidental pulmonary embolism detection (June 2026), Siemens Healthineers' integration of a generative AI structured reporting assistant (March 2026), Lunit's expansion of chest X-ray AI analysis software into new international markets (February 2026), and GE Healthcare's launch of a cloud-based AI orchestration platform (November 2025).
Technological Advancements
Rapid advancements in artificial intelligence, deep learning, computer vision, cloud computing, and advanced visualization are transforming the Medical Image Analysis Software Market. Deep convolutional neural networks and transformer-based vision models trained on large, multi-institutional imaging datasets now triage studies by urgency, flag incidental findings, and generate structured, quantifiable measurements that were previously dependent on manual radiologist annotation.
These algorithms are increasingly embedded directly into PACS and RIS workflows, prioritizing critical findings such as intracranial hemorrhage, pulmonary embolism, and large-vessel occlusion for immediate radiologist review, thereby compressing time-to-diagnosis in acute care settings. Generative AI is further extending into automated structured reporting, where natural language generation models draft preliminary radiology reports from image findings, and into synthetic data generation, which augments limited training datasets for rare disease detection algorithms while preserving patient privacy.
Consumer Adoption Patterns
Hospitals, diagnostic imaging centers, academic and research institutions, and specialty clinics are increasingly adopting medical image analysis software to improve diagnostic interpretation, reduce reporting turnaround time, and enhance clinical decision-making. The growing availability of cloud-based and hybrid deployment models is making these solutions more accessible to organizations of all sizes, while AI-assisted workflow tools are becoming standard expectations in high-volume imaging departments.
Regulatory Environment
The regulatory landscape for medical image analysis software is shaped by agencies that balance accelerated access for clinically valuable AI algorithms with rigorous evidence requirements for diagnostic accuracy and safety. In the United States, the FDA's Center for Devices and Radiological Health has demonstrated receptivity to novel AI/ML-based software as a medical device (SaMD) submissions, clearing a growing number of computer-aided detection and quantification algorithms through the 510(k) and De Novo pathways based on multi-reader, multi-case validation evidence. In Europe, CE marking under the Medical Device Regulation and the European Society of Radiology's advocacy for standardized AI validation shape market access.
Market Challenges
The Medical Image Analysis Software Market faces challenges related to high implementation costs, interoperability barriers with legacy imaging infrastructure, algorithm bias, cybersecurity vulnerabilities, data quality issues, and the need for continuous algorithm validation and monitoring. Additionally, reimbursement variability across regions and the administrative burden of regulatory compliance can slow adoption, particularly among smaller healthcare organizations.
Future Outlook
The future of the Medical Image Analysis Software Market remains highly promising as diagnostic imaging volumes continue to rise and healthcare systems increasingly adopt AI-assisted workflow tools. Increasing integration of generative AI into structured reporting, expansion of cloud-based and hybrid imaging infrastructure, growth of precision imaging and radiomics, and ongoing regulatory clearances for novel AI algorithms are expected to drive strong market growth during the forecast period, with the market projected to reach USD 14.0 billion by 2035 at a CAGR of 8.0%.
FAQs
What is the expected size of the Medical Image Analysis Software Market in 2026?
The market is expected to reach USD 7.0 billion in 2026.
What is the projected market value by 2035?
The market is forecast to reach USD 14.0 billion by 2035.
What is the CAGR of the Medical Image Analysis Software Market?
The market is expected to grow at a CAGR of 8.0% during 2026–2035.
Which software type segment dominates the market?
Integrated software is projected to dominate with 58.4% share in 2026.
Which region leads the global medical image analysis software market?
North America is poised to lead with 41.6% revenue share in 2026.
Summary of Key Insights
The Global Medical Image Analysis Software Market is expected to grow from USD 7.0 billion in 2026 to USD 14.0 billion by 2035, recording a CAGR of 8.0% during the forecast period. Integrated software leads the software type segment with 58.4% share, while cloud-based deployment dominates with 44.7% share. Computed tomography leads imaging modalities with 31.6% share, 3D imaging leads image types with 43.5% share, oncology leads clinical applications with 27.8% share, and hospitals lead end users with 61.9% share. North America holds the largest regional share with 41.6% of global revenue in 2026, while Asia Pacific is projected as the fastest-growing region at 9.9% CAGR. The US market is projected to reach USD 4.7 billion by 2035 at a CAGR of 7.5%.
Related Reports:
- https://dimensionmarketresearch.com/report/3d-image-sensors-market/
- https://dimensionmarketresearch.com/report/additive-manufacturing-for-medical-devices-market/

 Bangla