U.S. Liquid Biopsy Market Size, Demands, Growth Analysis, Industry Report 2026-2034
IMARC Group has recently released a report titled "U.S. Liquid Biopsy Market Size, Share, Trends and Forecast by Product and Service, Circulating Biomarker, Cancer Type, End User, and Region, 2026-2034", providing a comprehensive analysis of market trends, competitive landscape, and regional dynamics.
U.S. Liquid Biopsy Market Size and Forecast 2026–2034
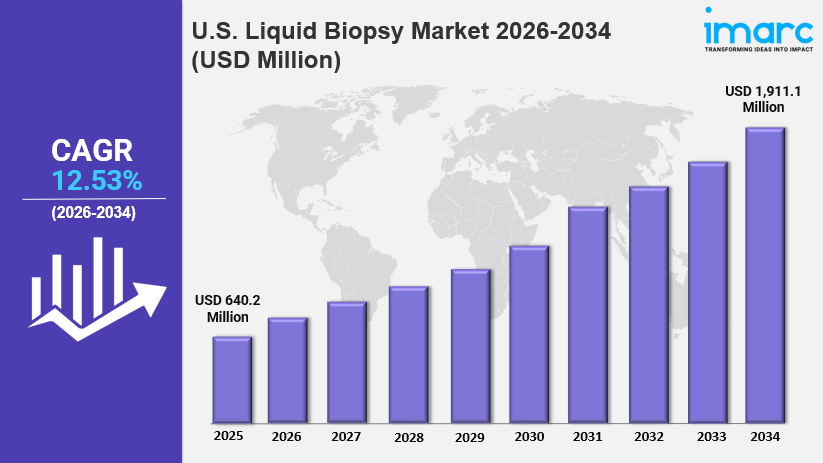
The U.S. liquid biopsy market reached USD 640.2 Million in 2025 and is projected to reach USD 1,911.1 Million by 2034, growing at a CAGR of 12.53% during 2026-2034. The market is growing due to rapid advances in next-generation sequencing (NGS), expanding clinical adoption of circulating tumor DNA (ctDNA) assays, and increasing reimbursement coverage. Applications are expanding from advanced non-small cell lung cancer (NSCLC) profiling into colorectal, breast, prostate, and multi-cancer screening, supported by a growing roster of FDA-approved companion diagnostic tests.
In 2026, the U.S. liquid biopsy market demand is being fueled by rising cancer incidence, with the American Cancer Society projecting 2.1 million new cancer diagnoses in the U.S. this year, continued expansion of CMS and commercial payer reimbursement, and the commercialization of multi-cancer early detection tests. The growing use of AI-enabled bioinformatics and the expansion of ctDNA-based minimal residual disease (MRD) monitoring are further broadening clinical adoption and intensifying competition among diagnostic companies.
Key Market Statistics at a Glance
- Base Year: 2025
- Historical Years: 2020–2025
- Forecast Period: 2026–2034
- Market Size (2025): USD 640.2 Million
- Projected Size (2034): USD 1,911.1 Million
- Growth Rate: CAGR of 12.53%
- Largest Region (2025): West (34.2% share)
- Leading Product and Service (2025): Kits and Reagents (46.8% share)
- Leading End User (2025): Hospitals and Laboratories (61.3% share)
Explore Opportunities in the U.S. Liquid Biopsy Market: Download the IMARC Sample Report: https://www.imarcgroup.com/united-states-liquid-biopsy-market/requestsample
U.S. Liquid Biopsy Market Growth: Key Trends and Market Insights
The U.S. liquid biopsy market growth is supported by rising cancer incidence and the need for earlier, more accurate, and less invasive detection, particularly for NSCLC, colorectal, and breast cancers. Liquid biopsy is a non-invasive approach that analyzes cancer-derived biomarkers, including ctDNA, circulating tumor cells (CTCs), cell-free RNA, and exosomes, from blood and other bodily fluids, providing real-time genomic information without tissue biopsy. Reimbursement is also expanding: Guardant Health’s Shield blood test for colorectal cancer screening received ADLT status from CMS, with reimbursement at USD 1,495 during an initial nine-month period starting April 2025, and a CMS Local Coverage Determination for ctDNA-based MRD testing finalized in 2024 is removing a major reimbursement barrier.
Key U.S. liquid biopsy market trends include accelerating adoption of ctDNA testing in solid tumors, with ctDNA-based comprehensive genomic profiling becoming standard of care for advanced NSCLC and colorectal cancer therapy selection by 2024. Multi-cancer early detection is also commercializing rapidly: GRAIL reported more than 370,000 Galleri tests ordered since its 2021 launch, and GRAIL and NHS England completed enrollment of 140,000 participants in the NHS-Galleri trial. NGS costs continue to decline, with the average cost per genome dropping by approximately 96% since 2013.
The U.S. liquid biopsy market growth is also being shaped by integration with AI-powered precision oncology platforms, which combine ctDNA results with health records, imaging, and treatment history, and by expansion of cell-free DNA analysis into organ transplant rejection surveillance, prenatal testing, and infectious disease monitoring. In April 2026, Tempus launched an automated active follow-up service that continuously tracks patient data and updates care recommendations in line with evolving clinical guidelines. These evolving market trends are expected to create opportunities for diagnostic companies through 2034.
Speak to an Analyst: https://www.imarcgroup.com/request?type=report&id=20364&flag=C
U.S. Liquid Biopsy Market Segmentation Analysis
The U.S. liquid biopsy market is segmented by product and service, circulating biomarker, cancer type, end user, and region, offering a comprehensive view of testing workflows, clinical applications, and regional dynamics across the country.
Breakup by Product and Service
- Kits and Reagents: Leads with a 46.8% share in 2025, reflecting the recurring consumable revenue model of NGS-based ctDNA workflows, where each patient sample requires fresh reagents.
- Services: Holds a 30.7% share, encompassing laboratory testing, bioinformatics interpretation, and physician reporting offered by commercial reference laboratories.
- Platforms and Instruments: Accounts for 22.5%, representing sequencers, digital PCR instruments, and automated liquid handling systems.
Breakup by Circulating Biomarker
- Circulating Tumor Cells: Retain clinical utility for prognosis in metastatic breast, prostate, and colorectal cancer, with FDA-cleared CTC enumeration.
- Extracellular Vesicles: An emerging area, including exosome profiling with potential in glioblastoma and pancreatic cancer.
- Circulating Tumor DNA: The dominant biomarker, underpinning NGS-based genomic profiling, MRD monitoring, and multi-cancer early detection.
- Others: Includes cell-free RNA and other circulating biomarkers under development.
Breakup by Cancer Type
- Lung Cancer: Anchored by ctDNA profiling for advanced NSCLC therapy selection and companion diagnostics.
- Breast Cancer: Supported by ctDNA-based MRD monitoring and CTC-based prognostic testing.
- Colorectal Cancer: Benefits from CMS coverage for ctDNA-based MRD testing and blood-based screening.
- Prostate Cancer: Supported by CTC-based prognostic use and expanding liquid biopsy applications.
- Liver Cancer: An emerging application area as liquid biopsy extends across solid tumors.
- Others: Includes additional cancer types and multi-cancer early detection applications.
Breakup by End User
- Hospitals and Laboratories: Leads with a 61.3% share in 2025, as centralized CLIA-certified laboratories process NGS-based liquid biopsy panels for hospital oncology departments.
- Academic and Research Centers: Holds a 25.4% share and acts as clinical evidence generator, with institutions such as MD Anderson, Memorial Sloan Kettering, and Dana-Farber setting protocols.
- Others: Includes additional healthcare providers and testing settings.
Breakup by Region
- West: Commands the largest share at 34.2% in 2025, driven by biotech hub density, leading research hospitals, and early technology adoption.
- Northeast: Holds 26.7%, anchored by academic medical centers, dense oncology networks, and payer coverage expansion.
- South: Accounts for 23.5%, supported by growing cancer incidence, hospital system expansion, and Medicaid broadening.
- Midwest: Holds 15.6%, driven by university hospital adoption and large integrated health systems.
Key Challenges and Growth Opportunities in the U.S. Liquid Biopsy Market
The U.S. liquid biopsy market faces several challenges that could affect its growth, including the high cost of comprehensive genomic profiling panels, which range from USD 3,000 to USD 7,500 per test, limited early-stage sensitivity, with ctDNA detection rates of 30–55% in early-stage disease, and the compliance burden created by the FDA’s laboratory developed test (LDT) final rule for smaller clinical laboratories. Clinical validation gaps and analytical variability across platforms also slow protocol adoption.
Despite these challenges, the market offers significant growth opportunities driven by companion diagnostic co-development with pharmaceutical companies, expansion of ctDNA-based MRD monitoring, and AI and bioinformatics-enhanced interpretation. Multi-cancer early detection, MRD monitoring, and AI-integrated analytics represent the highest-growth investment areas through 2034, while community oncology practices are an emerging opportunity for broader adoption. Companies investing in clinical validation, reimbursement coverage, and regulatory approvals will be well positioned to strengthen their competitive advantage through 2034.
Competitive Landscape
The U.S. liquid biopsy market features a dual competitive structure. At the FDA-approved companion diagnostic level, the market is highly concentrated, with Guardant Health, Inc. and F. Hoffmann-La Roche Ltd together accounting for approximately 55–60% of companion diagnostic liquid biopsy test volume in 2025. Below that tier, the market is fragmented, with more than 80 CLIA-certified laboratories offering ctDNA testing. Key companies include Guardant Health, Inc., F. Hoffmann-La Roche Ltd, GRAIL, Inc., Illumina, Inc., and Biodesix.
The report provides a comprehensive analysis of the competitive landscape, including market structure, key player positioning, top winning strategies, competitive dashboard, and company evaluation quadrant, along with detailed profiles of major companies operating in the space. Market participants are investing in companion diagnostic partnerships, multi-cancer early detection, MRD monitoring, and AI-enabled analytics to strengthen their positioning and meet growing clinical demand.
Latest News and Developments
- April 2026: Tempus launched an automated active follow-up service that continuously tracks patient data and updates care recommendations in line with evolving clinical guidelines.
- March 2026: Guardant Health, Inc. announced it will present 28 scientific abstracts at AACR 2026, highlighting advancements in tumor typing, therapy selection, and the expanded utility of both multi-omic tissue and liquid biopsy testing.
- November 2024: The U.S. FDA approved FoundationOne Liquid CDx, from Roche subsidiary Foundation Medicine, as a companion diagnostic for non-small cell lung cancer. The test uses next-generation sequencing of ctDNA to analyze more than 300 cancer-related genes.
Author IMARC Group
IMARC Group is a leading global market research company providing data-driven insights and expert consulting services to businesses seeking to achieve their strategic objectives. With a multidisciplinary team of industry experts, IMARC delivers reliable market intelligence across sectors including Chemicals and Materials, Healthcare, Technology, Agriculture, and Retail.
Contact Us:
IMARC Group
Email: [email protected]
United States: +1-201-971-6302

 Bangla