Automotive Parts Packaging Market Size, Share & Forecast 2033
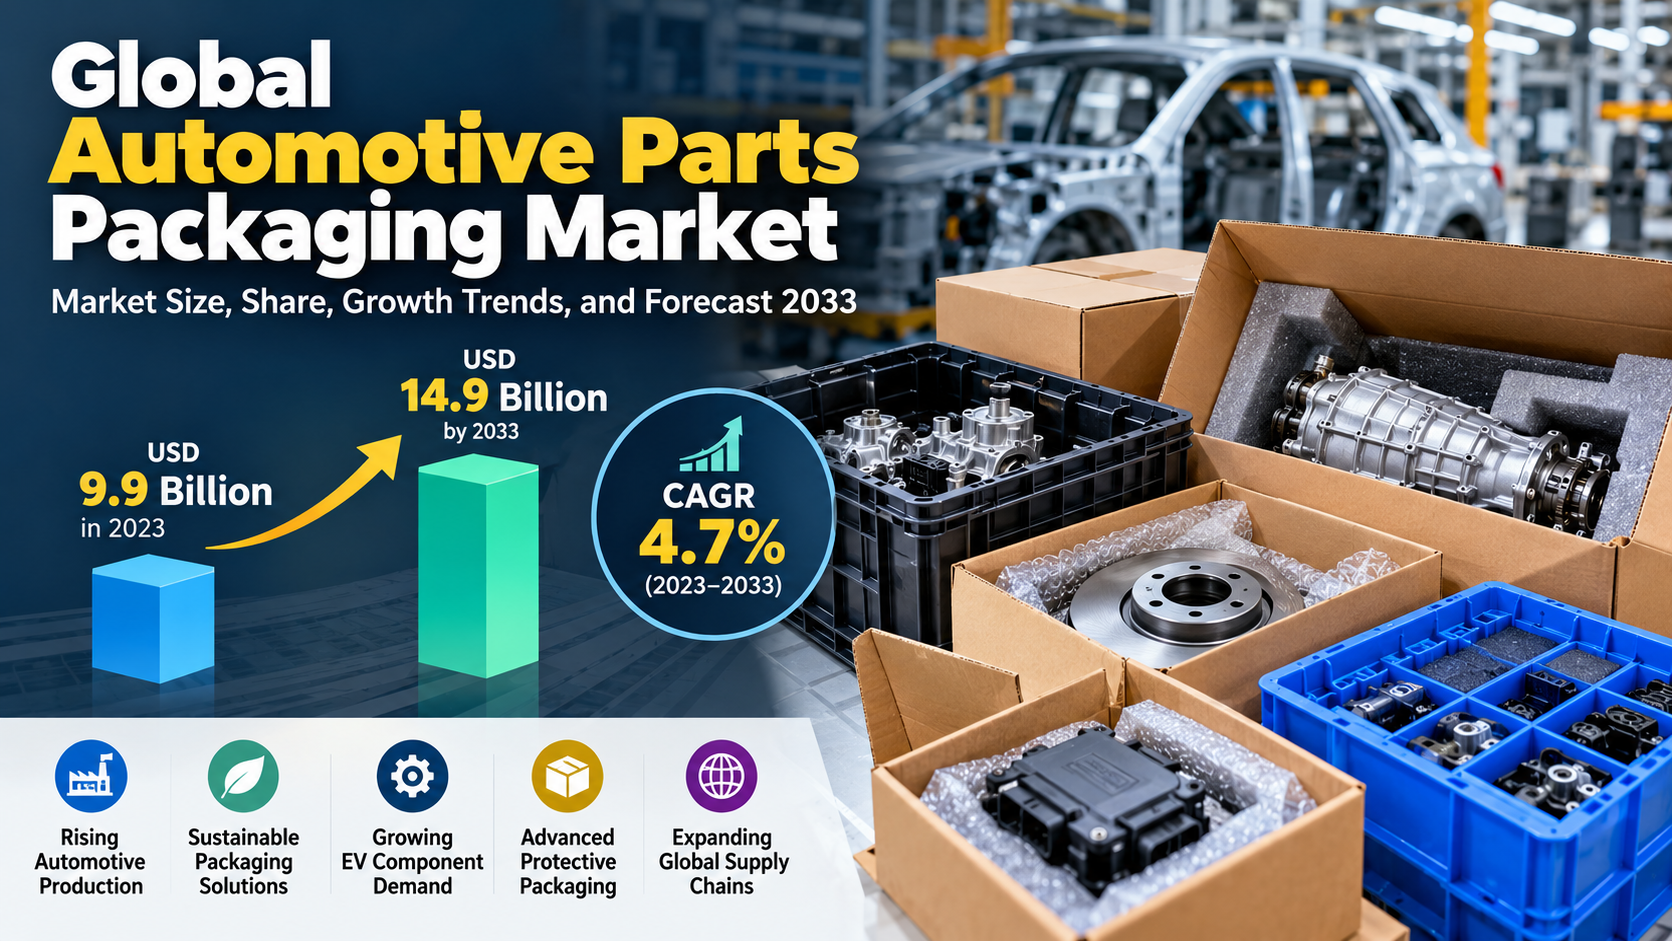
The Global Automotive Parts Packaging Market is undergoing a significant transformation as automotive manufacturers focus on improving product protection, reducing transportation expenses, and building more efficient supply chains. Valued at USD 9.9 billion in 2023, the market is anticipated to reach USD 14.9 billion by 2033, registering a CAGR of 4.7%. Increasing automotive component production, growing aftermarket distribution, and rising demand for specialized packaging solutions are creating favorable conditions for industry expansion.
Modern automotive supply chains depend on the secure movement of mechanical assemblies, electrical systems, batteries, sensors, and replacement components. Each product requires packaging designed around its physical characteristics, handling requirements, and transportation conditions. From corrugated containers and cushioning materials to returnable pallets and custom-engineered crates, packaging has become an essential element of automotive manufacturing and distribution.
The growing adoption of electric vehicles, connected automotive systems, and digital spare parts platforms is introducing new packaging requirements. Manufacturers must increasingly protect sensitive electronic components while maintaining affordable logistics operations. At the same time, sustainability considerations are encouraging businesses to evaluate recyclable materials, reusable transportation systems, and packaging designs that minimize unnecessary material consumption.
📄 Looking for Specific Data? Get a Free Customized Sample:
https://dimensionmarketresearch.com/request-sample/automotive-parts-packaging-market/
Automotive Parts Packaging Market Overview
Automotive parts packaging refers to protective materials and packaging systems used to preserve vehicle components during storage, handling, and shipment. These solutions help maintain product quality by preventing mechanical damage, moisture exposure, contamination, scratches, and corrosion.
Unlike conventional consumer packaging, automotive component packaging frequently needs to accommodate heavy products, irregular shapes, delicate circuitry, and long-distance transportation. Packaging suppliers therefore develop application-specific solutions that combine structural strength with practical handling and storage capabilities.
The market serves original equipment manufacturers (OEMs), component suppliers, spare parts distributors, logistics operators, and automotive service networks. As vehicle designs become increasingly complex, packaging solutions must also adapt to changing component specifications and distribution models.
Key Findings and Market Statistics
-
2023 Market Revenue: USD 9.9 billion.
-
2033 Revenue Forecast: USD 14.9 billion.
-
Forecast CAGR: 4.7%.
-
Asia Pacific Revenue Share: 46.4% in 2024.
-
Disposable Packaging Share: 63.1% in 2024.
-
Electrical Components Share: 34.5% in 2024.
-
Leading Product Segment: Protective packaging.
-
Major Opportunity: Sustainable and customized solutions.
These indicators demonstrate how demand for reliable packaging continues to expand alongside developments in automotive technology, manufacturing practices, and global distribution infrastructure.
Automotive Parts Packaging Market Dynamics
Growth Drivers: Why Is Demand for Automotive Packaging Increasing?
Expanding Automotive Production and International Trade
Automotive manufacturing involves numerous suppliers producing components across different locations. Engines, braking systems, electrical modules, filters, and cooling assemblies frequently travel between production facilities before reaching final vehicle assembly lines.
This geographically distributed manufacturing structure increases the need for dependable packaging systems that protect component quality throughout transportation.
Packaging solutions also contribute to operational efficiency by simplifying warehouse storage, product identification, material handling, and inventory management. Standardized packaging can improve the movement of components through manufacturing facilities while reducing the possibility of handling-related damage.
The leading demand drivers include:
-
Increasing automotive component production.
-
Expansion of international supply networks.
-
Rising vehicle maintenance requirements.
-
Greater demand for secure component transportation.
-
Growing automotive aftermarket distribution.
Greater Use of Sustainable Packaging Materials
Automotive companies are evaluating packaging materials that support resource conservation and waste reduction. Recycled cardboard, molded pulp, reusable containers, and lightweight protective materials are gaining importance across packaging procurement strategies.
Businesses are also redesigning packaging to remove excess material without reducing protection. These improvements can lower shipping weight, improve container utilization, and reduce packaging-related disposal costs.
Market Restraints: Cost Pressures and Operational Challenges
Despite favorable growth opportunities, the industry faces several obstacles. Changes in raw material prices can increase manufacturing expenses, particularly for packaging systems relying on paperboard, plastics, resins, and specialized cushioning materials.
Moreover, reusable packaging requires investments in durable containers, collection processes, tracking technology, and reverse logistics networks. Companies operating across widely dispersed shipping destinations may find these systems difficult to implement economically.
Other important barriers include:
-
Fluctuating packaging material costs.
-
High upfront reusable packaging investments.
-
Transportation and supply chain disruptions.
-
Increasing pressure to minimize packaging waste.
-
Complex handling of fragile automotive electronics.
Packaging suppliers must continuously improve efficiency while maintaining the protection standards expected by automotive customers.
Emerging Trends Reshaping Automotive Parts Packaging
Shift Toward Returnable Packaging Systems
Returnable packaging is becoming increasingly relevant within automotive manufacturing networks that operate predictable transportation routes.
Reusable crates, foldable containers, metal racks, and engineered plastic pallets can withstand repeated handling cycles. When correctly managed, these systems reduce dependence on single-use packaging and improve long-term material efficiency.
However, their financial advantages depend on sufficient reuse frequency, efficient container recovery, and manageable transportation costs.
Smart Packaging and Digital Traceability
Digital technologies are influencing how automotive components are packaged, identified, and monitored throughout distribution.
RFID labels, QR codes, and connected inventory platforms provide improved visibility into packaged goods. These capabilities support shipment tracking, warehouse coordination, and component identification.
Artificial intelligence and automated inspection systems can also assist with packaging design and quality control.
Key technology trends include:
-
RFID-based shipment identification.
-
AI-supported packaging optimization.
-
Automated inspection of packaging defects.
-
Smart inventory and warehouse integration.
-
Digitally traceable automotive components.
Growing Importance of Electric Vehicle Packaging
Electric vehicles incorporate advanced electronic systems, battery components, power control modules, and sensitive electrical assemblies.
These technologies require packaging designed for appropriate protection against vibration, moisture, electrostatic discharge, and other transportation-related risks.
Battery systems may also require additional safety-oriented packaging design and handling procedures depending on the component type and shipping conditions.
Consequently, suppliers capable of delivering specialized packaging for electric mobility applications have opportunities to expand their product portfolios.
Automotive Parts Packaging Market Segmentation Overview
The industry can be examined across packaging type, product category, and automotive component application. Each category reflects different performance requirements and purchasing considerations.
By Packaging Type: Disposable Packaging Maintains Leadership
Disposable packaging is projected to represent 63.1% of market revenue in 2024, making it the leading packaging category.
Its widespread use is supported by comparatively low initial costs, design flexibility, and suitability for one-way automotive shipments. Corrugated boxes, protective films, and cushioning systems are commonly used when components move across distribution networks without established return channels.
Reusable packaging represents an important alternative, particularly where manufacturers regularly transport parts between the same facilities.
By Product Type: Protective Packaging Leads Demand
Protective packaging is anticipated to maintain a leading position among product categories, reflecting the importance of minimizing transportation damage and preserving component functionality.
Specialized protective materials can absorb shocks, reduce vibration, prevent scratching, and shield automotive parts from environmental exposure.
The major product segments include:
-
Protective Packaging: Cushioning and damage prevention.
-
Crates: Transportation of large automotive components.
-
Pallets: Handling and storage of heavy products.
-
Bags and Pouches: Protection for smaller components.
-
Bulk Containers and Cases: High-volume industrial shipments.
-
Folding Cartons: Lightweight secondary packaging.
-
Trays: Organized positioning of individual parts.
-
Corrugated Products: Versatile and recyclable packaging.
Packaging selection depends on the dimensions, weight, sensitivity, shipment frequency, and required protection level of each automotive component.
By Component: Electrical Components Hold the Largest Share
Electrical components are expected to account for 34.5% of market revenue in 2024, positioning them as the leading component application.
The growing integration of sensors, wiring systems, control modules, electronic devices, and advanced vehicle technologies is increasing the importance of packaging specifically engineered for electrical products.
Other applications include automotive filters, batteries, cooling systems, and various mechanical components.
As the automotive industry transitions toward more electronically sophisticated vehicles, packaging manufacturers are expected to face increasing demand for precision-focused solutions.
Automotive Parts Packaging Market Growth Opportunities
Automotive E-Commerce Creates Demand for Individualized Packaging
The expansion of online automotive parts retail is changing distribution practices. Instead of transporting components exclusively in bulk quantities, suppliers increasingly fulfill smaller orders shipped directly to workshops, retailers, and individual customers.
These shipments require packaging capable of protecting products throughout sorting, transportation, and last-mile delivery.
Customized boxes, shock-absorbing inserts, protective pouches, and appropriately sized containers can help businesses minimize damage-related returns while controlling shipping expenses.
Packaging Customization Offers Competitive Advantages
Vehicle components differ considerably in geometry, weight, fragility, and environmental sensitivity. Standard packaging solutions may therefore provide insufficient protection or require unnecessary material consumption.
Custom-engineered packaging allows suppliers to develop solutions around precise product dimensions and handling requirements.
Manufacturers offering packaging design, prototype testing, material selection, and logistics optimization may strengthen relationships with automotive customers.
Automotive Parts Packaging Market Competitive Landscape
Competition in the automotive parts packaging industry is shaped by product performance, affordability, material innovation, manufacturing capabilities, and customer-specific engineering expertise.
Packaging providers seek long-term relationships with automotive OEMs, Tier 1 component suppliers, and aftermarket distributors by offering integrated packaging services.
The ability to deliver consistent quality across multiple manufacturing locations is particularly important for international automotive supply chains.
Key Companies Operating in the Market
Prominent companies identified in the industry's competitive landscape include:
-
Nefab AB
-
Mondi Plc
-
Knauf Industries
-
Smurfit Kappa Group
-
WestRock Company
-
Sonoco Products
-
DS Smith
-
Signode India
-
Schoeller Allibert Services
-
Sealed Air Corporation
These names reflect the report's competitive coverage, while individual corporate structures may have changed since its publication.
Industry participants increasingly emphasize recyclable materials, durable returnable systems, protective packaging design, and production process improvements.
Strategic differentiation is expected to depend on reducing customers' total packaging and transportation costs rather than simply offering the lowest packaging price.
📄 Purchase the report for comprehensive details:
https://dimensionmarketresearch.com/checkout/automotive-parts-packaging-market/
Automotive Parts Packaging Market Regional Analysis
Asia Pacific: Leading Regional Market
Asia Pacific is projected to account for 46.4% of global automotive parts packaging revenue in 2024, maintaining its position as the largest regional market.
The region benefits from extensive vehicle manufacturing activity, established automotive component supplier networks, and competitive industrial packaging production.
China plays a central role through its large automotive manufacturing base and expanding electric vehicle ecosystem. These developments create opportunities for advanced protective packaging, specialized containers, and logistics-oriented packaging solutions.
Japan, India, and South Korea also contribute to regional demand through automotive manufacturing, component exports, and technological development.
International packaging providers can pursue opportunities by combining advanced engineering capabilities with locally competitive production and distribution models.
North America: Focus on Efficiency and Advanced Packaging
North America represents an established market supported by automotive manufacturing operations, replacement parts distribution, and industrial logistics infrastructure.
The United States and Canada provide opportunities for protective packaging, reusable containers, automated handling systems, and specialized solutions for electrical components.
Companies are increasingly evaluating packaging performance in relation to transportation efficiency, material consumption, and long-term operating costs.
Europe: Emphasis on Resource Efficiency
European automotive packaging demand is influenced by established vehicle manufacturing industries and increasing attention to sustainable materials.
Germany, France, Italy, and the United Kingdom remain important markets for component packaging solutions.
Returnable transportation systems, recyclable protective materials, and efficient container designs present opportunities for suppliers serving European automotive manufacturers.
Latin America, Middle East, and Africa
Latin American demand is supported by automotive production and component distribution, particularly in Mexico and Brazil.
In the Middle East and Africa, automotive aftermarket development, vehicle servicing requirements, and industrial investment contribute to packaging demand.
Although regional market conditions differ, expanding distribution networks may support additional opportunities for protective and industrial packaging suppliers.
Future Outlook: What Will Drive the Market Through 2033?
The global automotive parts packaging industry is forecast to grow steadily as manufacturers respond to evolving vehicle technologies and logistics requirements.
The anticipated increase to USD 14.9 billion by 2033 reflects opportunities in traditional mechanical components as well as electronic systems, batteries, and specialized automotive assemblies.
Sustainability will remain an important consideration, encouraging manufacturers to improve material utilization and evaluate packaging alternatives based on their environmental and economic performance.
Digital technologies are also expected to play a larger role in packaging design, quality assurance, and shipment visibility.
Key future priorities include:
-
Expanding specialized electric vehicle packaging.
-
Improving recyclable packaging performance.
-
Increasing use of reusable transportation systems.
-
Developing lightweight protective materials.
-
Integrating automated packaging inspection.
-
Strengthening automotive e-commerce logistics.
Companies that successfully combine protective performance, customization, and cost efficiency may be better positioned to capture emerging demand.
Frequently Asked Questions (FAQs)
1. How large is the Global Automotive Parts Packaging Market?
The market was valued at USD 9.9 billion in 2023 and is forecast to reach USD 14.9 billion by 2033, reflecting a CAGR of 4.7%.
2. Which region leads the automotive parts packaging industry?
Asia Pacific is expected to lead with a 46.4% revenue share in 2024, supported by its extensive automotive manufacturing and component supply networks.
3. What is driving growth in automotive parts packaging?
Growth is being supported by increasing component transportation, automotive aftermarket expansion, electric vehicle production, and demand for protective and sustainable packaging.
4. Which segments account for the largest market shares?
Disposable packaging is projected to hold 63.1% of revenue in 2024, while electrical components are expected to represent 34.5% of the market by component.
5. What opportunities exist for automotive packaging manufacturers?
Important opportunities include recyclable materials, reusable containers, electric vehicle component protection, customized packaging, smart tracking technologies, and automotive e-commerce distribution.
Summary of Key Market Insights
The Global Automotive Parts Packaging Market is evolving as automotive manufacturers increasingly recognize packaging as an important contributor to product protection, supply chain reliability, and operational efficiency.
With projected growth from USD 9.9 billion in 2023 to USD 14.9 billion by 2033, the industry offers opportunities for companies developing advanced protective materials, specialized transportation containers, and environmentally responsible packaging solutions.
Asia Pacific's anticipated leadership, the strong position of disposable packaging, and rising requirements for electrical component protection demonstrate the industry's diverse sources of demand.
Looking ahead, innovation in sustainable materials, packaging customization, automation, and logistics integration will help determine competitive success. Businesses that align their solutions with changing automotive manufacturing requirements are likely to benefit from the expanding role of packaging across global vehicle supply chains.
Related Reports:
https://dimensionmarketresearch.com/report/automotive-thermoformed-plastics-parts-packaging-market/
https://dimensionmarketresearch.com/report/packaging-market/
https://dimensionmarketresearch.com/report/packaging-automation-market/

 Bangla