

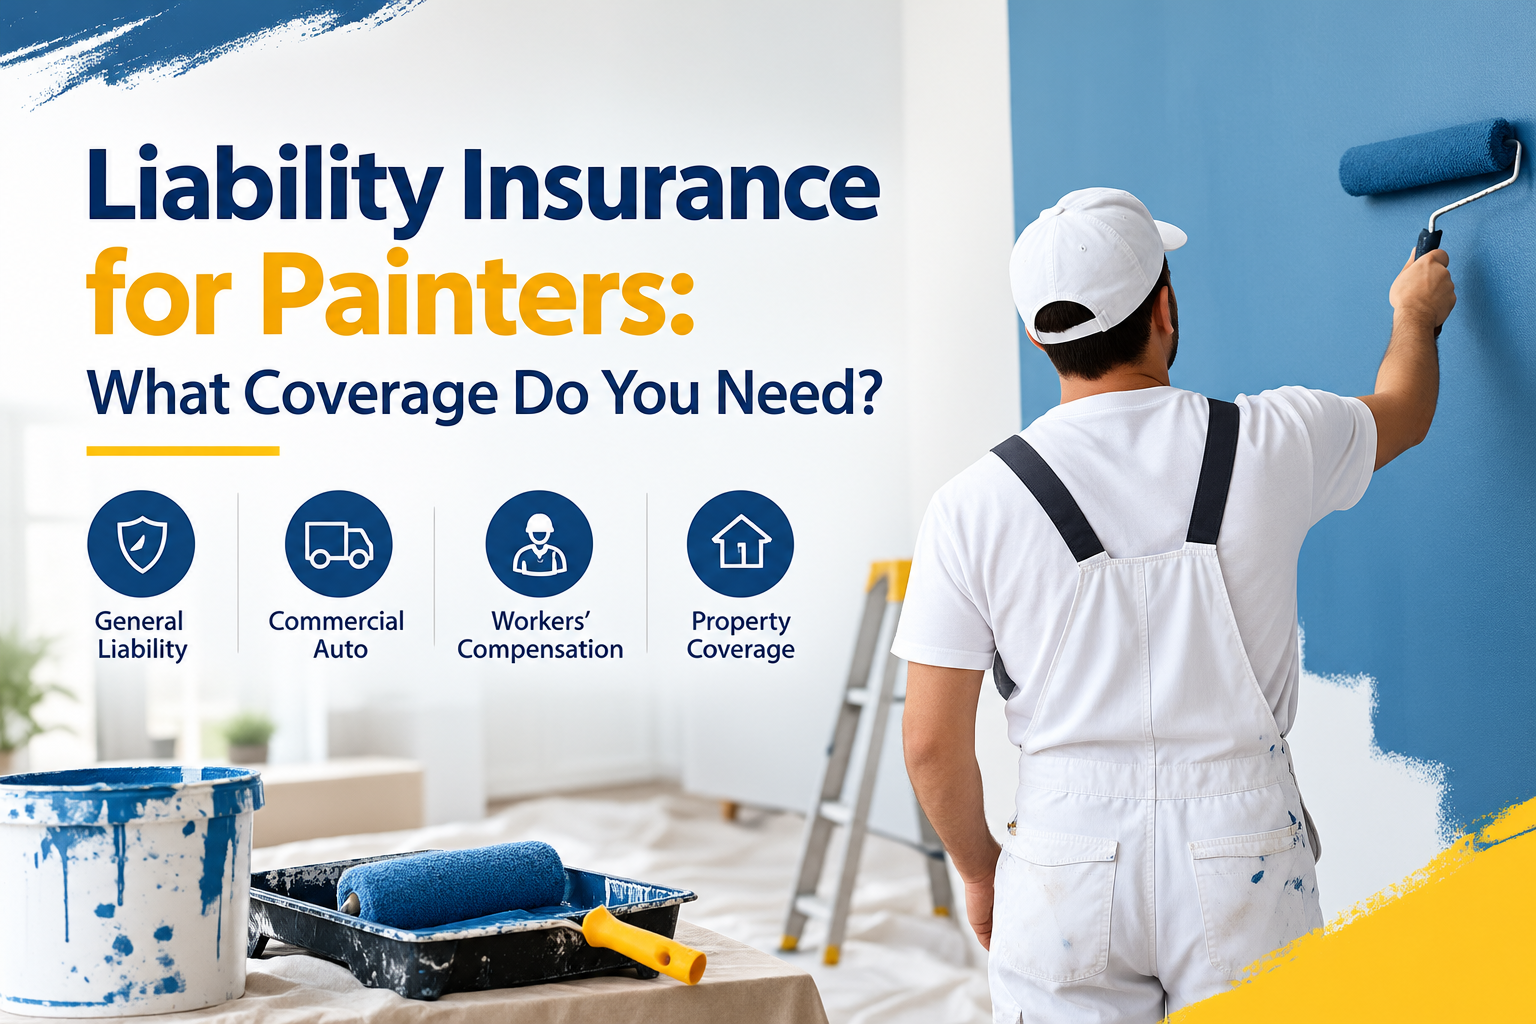
Painting may look straightforward, but running a painting business comes with risks that can become expensive quickly. A customer could trip over equipment, paint could spill onto expensive flooring, or a completed project could result in a dispute over property damage. Liability insurance for painters can help protect your business from many of these unexpected costs.
Whether you work as an independent painter, operate a small painting company, or manage several employees, having the right coverage can help protect your finances and give customers greater confidence in your services.
Why Do Painters Need Liability Insurance?
Painters work inside homes, offices, retail spaces, commercial buildings, and construction sites. Every job creates potential risks involving customers, employees, property, tools, and third parties.
For example, imagine that you are painting a customer's living room. While moving equipment, a ladder accidentally damages a wall or breaks a valuable fixture. The customer may expect you to pay for the repairs. Without appropriate insurance, those costs could come directly from your business income.
General liability coverage is designed to address certain third-party claims involving bodily injury, property damage, and personal or advertising injury, subject to the policy terms, conditions, exclusions, and limits.
For many painting businesses, this type of protection is an important part of a broader insurance strategy.
What Does Liability Insurance for Painters Typically Cover?
The exact protection depends on the policy and insurer, but general liability insurance commonly addresses several types of business risks.
Property Damage
Property damage is one of the most obvious risks for painters. A paint spill, accidental damage to flooring, or damage to a customer's furniture can potentially lead to a claim.
Liability coverage may help with eligible third-party property damage claims, depending on the circumstances and policy provisions.
Bodily Injury to Third Parties
A customer or visitor could fall over a drop cloth, extension cord, ladder, or other equipment at a job site. If someone is injured and claims that your business is responsible, a covered liability policy may help with eligible expenses and legal defense.
Personal and Advertising Injury
Some liability policies also provide protection for certain claims involving personal or advertising injuries. These can include specific allegations such as libel or slander, subject to policy terms and exclusions.
Legal Defense Costs
A liability claim can become expensive even when the allegation is ultimately unsuccessful. Depending on the policy, liability insurance may provide legal defense for covered claims.
This can be especially important for small painting companies that may not have substantial financial resources available for unexpected legal expenses.
Is General Liability Enough for a Painting Business?
Not always. General liability is valuable, but it does not automatically cover every risk a painter faces.
For example, liability insurance generally does not replace workers' compensation coverage for employees. It also may not cover damage to your own tools, vehicles, or equipment.
A painter should consider the full range of risks associated with the business before deciding what coverage is appropriate.
If you have employees, workers' compensation requirements may apply based on the state where you operate. If you use business vehicles, commercial auto insurance may also be necessary.
The goal is to build coverage around the actual way your business operates rather than purchasing a policy based only on price.
Other Insurance Coverage Painters May Need
Liability protection is only one part of insurance for contractors. Depending on your business structure, employees, vehicles, equipment, and projects, additional policies may be useful.
Workers' Compensation
If your painting company has employees, workers' compensation can provide benefits for qualifying work-related injuries and illnesses. Requirements vary by state, so business owners should understand the rules that apply where they operate.
Commercial Auto Insurance
A personal auto policy may not provide the coverage needed when a vehicle is regularly used for business purposes. Painters who transport ladders, paint, tools, or other equipment may need commercial vehicle coverage.
Tools and Equipment Coverage
Professional painters often invest significant money in sprayers, ladders, compressors, scaffolding, power tools, and other equipment. Coverage for business property or equipment may help protect these assets against certain covered losses.
Inland Marine Coverage
Painters frequently transport tools and equipment between locations. Depending on the policy, inland marine insurance can provide protection for certain business property while it is being transported or used away from the primary business location.
Commercial Property Insurance
If you operate from a dedicated office, workshop, or storage facility, commercial property insurance may help protect eligible business property and the building, depending on what you own and the policy structure.
How Much Liability Coverage Should a Painter Carry?
There is no single coverage limit that works for every painting business.
A solo painter working on small residential projects may have different insurance needs from a contractor handling large commercial properties. Your contracts, project size, number of employees, annual revenue, and type of work can all influence your coverage needs.
Some customers, property managers, general contractors, or commercial clients may also require contractors to carry specific liability limits before work begins.
Before choosing limits, review your contracts and consider the potential financial impact of a significant claim.
How Can Painters Keep Insurance Costs Under Control?
Insurance does not have to be approached as simply finding the cheapest policy. A policy that lacks important protection may leave your business exposed when you need coverage most.
Start by maintaining accurate information about your business. Tell your insurance professional what types of painting work you perform, where you work, whether you use employees or subcontractors, and what equipment you use.
You can also reduce avoidable risks by keeping job sites organized, training workers on ladder and equipment safety, protecting customers' belongings, and documenting projects carefully.
A strong safety process may not eliminate claims, but it can reduce preventable accidents and demonstrate that your business takes risk management seriously.
What Should Painters Check Before Buying a Policy?
Before purchasing liability coverage, look beyond the premium. Review the policy limits, deductibles, exclusions, covered operations, and any special conditions that may affect your work.
Also check whether the policy accurately describes your business activities. A painter who performs additional services, such as drywall repair, pressure washing, carpentry, or exterior restoration, should make sure those operations are properly disclosed.
If a customer requires a certificate of insurance, confirm that the policy can provide the documentation needed for the contract.
Protect Your Painting Business Before a Claim Happens
Running a painting business means dealing with risks that are difficult to predict. A simple accident can result in property damage, an injury allegation, or a costly legal dispute.
The right liability insurance for painters can provide an important layer of financial protection against covered third-party claims. However, general liability should be considered as part of a broader business protection strategy rather than as the only insurance a painter may need.
Take time to evaluate your projects, employees, vehicles, equipment, contracts, and business property. Understanding those risks can help you choose coverage that fits the way your painting business actually operates and avoid unpleasant surprises when a claim occurs.
