

US Cards and Payments Industry Outlook: Digital Innovation, Consumer Trends, and Business Opportunities
Digital Transformation Reshapes the Payments Landscape
The United States cards and payments industry is evolving as consumers and businesses increasingly rely on convenient, secure, and flexible transaction methods. Debit cards, credit cards, prepaid cards, mobile wallets, and electronic transfers are contributing to a diverse payments ecosystem that supports retail purchases, e-commerce, business transactions, and cross-border spending. As digital commerce expands and payment technologies advance, financial institutions, payment processors, and technology providers are investing in solutions designed to simplify transactions, improve customer experiences, and strengthen payment security. These developments are creating opportunities for established financial services companies and innovative fintech businesses.
A comprehensive market assessment by Markntel Advisor examines the US Cards and Payments Market, covering industry developments and forecasts for 2025–2030. The industry is being shaped by evolving consumer payment preferences, growing digital commerce activity, technological advancements, and competition among financial institutions and payment service providers. The report evaluates key segments, including debit, credit, and prepaid cards; mobile wallets and other payment instruments; business and consumer transactions; domestic and foreign payments; and applications spanning groceries, healthcare, travel, and hospitality. These areas offer businesses opportunities to refine their strategies and respond to changing payment needs.
Card Payments Remain Central to Everyday Transactions
Debit and credit cards continue to play an important role in everyday spending across the United States. Debit cards provide consumers with direct access to funds held in bank accounts, while credit cards offer access to revolving credit and may include rewards or other benefits, depending on the product. Prepaid cards serve additional use cases, including controlled spending and selected business or consumer payment needs.
The Federal Reserve's 2025 Payments Study reports that consumers and businesses made 236.6 billion noncash payments in 2024. Cards accounted for approximately 79% of these transactions by number, while debit cards represented the majority of card payments. These findings demonstrate the importance of card-based transactions within the broader US payments ecosystem.
For financial institutions and payment providers, this activity creates opportunities to improve transaction processing, develop customer-focused products, and offer convenient payment experiences. Businesses that prioritize reliability, accessibility, and transparent services can strengthen customer engagement across multiple spending categories.
Mobile Wallets and E-Commerce Expand Opportunities
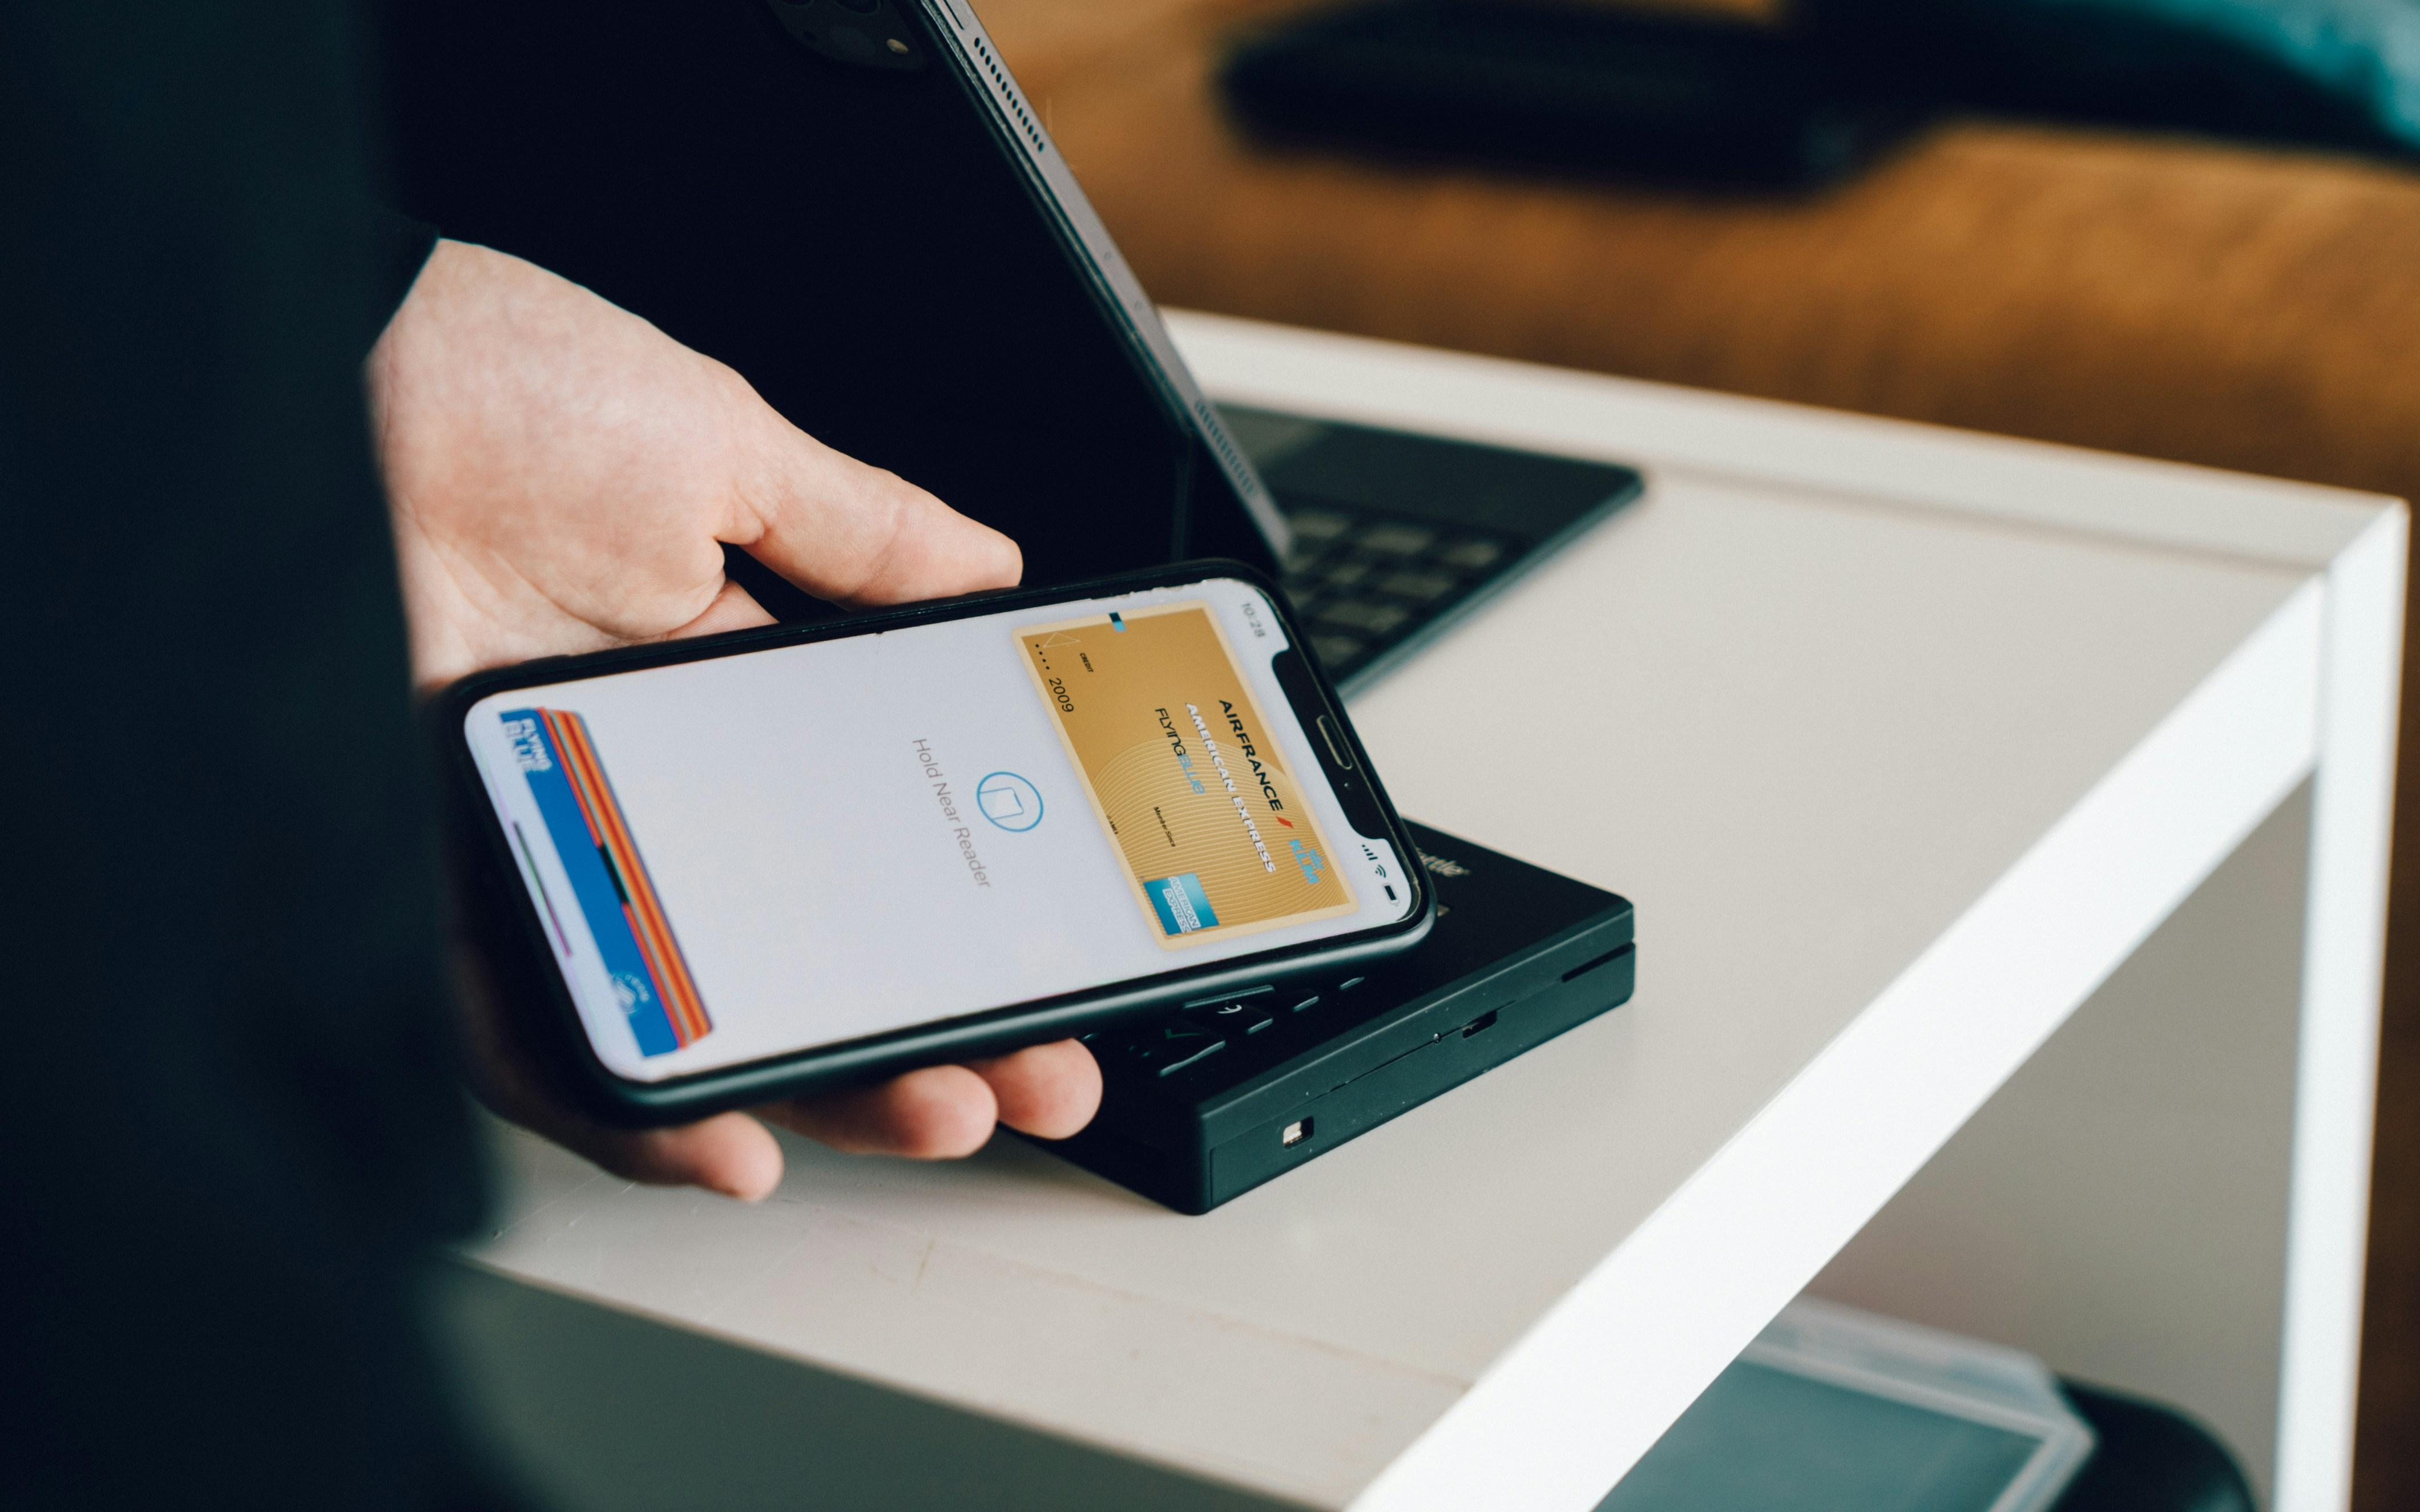
Mobile wallets and digital payment solutions are changing how consumers interact with merchants. By enabling payment credentials to be stored on compatible devices, mobile wallets can make checkout more convenient across online and in-person environments. Their integration with e-commerce platforms, mobile applications, and point-of-sale terminals is encouraging payment providers to develop more connected customer experiences.
For merchants, a broader selection of payment options can help simplify checkout and accommodate different consumer preferences. Payment service providers can also explore opportunities through digital onboarding, integrated transaction reporting, and solutions that connect online and physical sales channels.
However, successful adoption depends on factors such as ease of use, merchant acceptance, transaction reliability, and effective protection of payment information. Providers that make digital payments intuitive while maintaining strong security controls may be better positioned to compete as consumer expectations evolve.
Innovation and Security Shape Industry Development
Technological innovation is an important competitive factor across the cards and payments ecosystem. Contactless payments, tokenization, automated fraud monitoring, and improvements in transaction processing can help providers enhance convenience and strengthen security. Data analytics may also support transaction monitoring and help financial institutions identify unusual activity, subject to applicable privacy and compliance requirements.
Security remains essential as payments become increasingly interconnected. Financial institutions, merchants, and payment processors must protect sensitive information, manage fraud risks, and maintain reliable systems. The Consumer Financial Protection Bureau provides consumer-focused information about credit cards, including account terms, fees, and protections. Clear communication and responsible product design can help providers build trust and support informed consumer decisions.
At the same time, companies must manage technology investment costs, evolving regulatory requirements, and competition from established payment networks and emerging fintech providers. Maintaining reliable services while introducing new capabilities will remain important to long-term competitiveness.
Competitive Landscape and Business Opportunities
The US cards and payments industry includes major banks, card issuers, payment networks, fintech businesses, digital wallet providers, and technology vendors. Companies compete through transaction reliability, product features, merchant acceptance, customer service, pricing, and technological capabilities.
Opportunities extend across consumer payments, business-to-business transactions, e-commerce, point-of-sale systems, and cross-border payments. Financial institutions can enhance their digital offerings, while merchants can improve checkout experiences through suitable payment integrations. Technology providers may find opportunities in fraud prevention, payment infrastructure, analytics, and systems integration.
Nevertheless, participants must navigate fraud risks, changing consumer expectations, transaction costs, and the technical complexity of maintaining secure payment environments. Strategic partnerships and investment in scalable infrastructure can help organizations adapt to evolving market conditions.
Future Outlook
The US cards and payments industry is expected to remain dynamic as card-based transactions, mobile wallets, and other electronic payment methods continue to develop. Opportunities will span digital commerce, payment security, customer experience, and integrated financial technology. Businesses that combine reliable transaction processing with accessible services, effective security measures, and ongoing innovation can strengthen their competitive position in the evolving US payments ecosystem.
